Insurance
Does homeowners insurance cover mold in Florida?
Whether mold costs are covered depends on your policy and the cause of the growth. This page covers general Florida claim rules, not what your policy pays.
How we work
English or Spanish
One call, in your language.
One point of contact
No searching. No lists of companies.
Independent assessment
By a licensed assessor you hire and pay directly.
Licensed remediation
We sell it; a Florida-licensed remediator performs it on our behalf.
What decides a mold claim
Coverage for mold depends on your policy and on the cause of the growth. Florida law sets parts of the claim process, and the policy language decides what is covered and what is excluded.
After a loss, review your own policy for duties such as giving prompt notice, protecting the property from further damage, keeping records, cooperating with the investigation and providing requested information. The duties and the consequences of not meeting them depend on your policy and current law.
Within 60 days after receiving notice of an initial, reopened or supplemental residential property claim, the insurer must pay or deny the claim or part of it unless a factor beyond its control applies, and must give a written explanation of the basis for payment, denial or partial denial.
- 7 calendar days
- To acknowledge a claim communication, with the exceptions in the statute
- 30 days
- For any physical inspection, after proof-of-loss statements
- 60 days
- To pay or deny a claim, with exceptions
- 14 days
- To provide the Homeowner Claims Bill of Rights
What Florida law sets
These are general rules for residential property claims. Deadlines have exceptions, and your policy and insurer decide your own claim.
Notice and response
Unless the statute or the policy provides otherwise, an insurer generally must acknowledge receipt of a claim communication within 7 calendar days, begin investigating within 7 days after receiving proof-of-loss statements, and conduct any physical inspection within 30 days after receiving them.
Pay or deny
Within 60 days after notice of an initial, reopened or supplemental residential claim, the insurer must pay or deny it or part of it, unless a factor beyond its control applies. The deadline is paused during mediation or when requested information is not provided, as the statute specifies.
Homeowner Claims Bill of Rights
An insurer issuing a personal lines residential property policy must provide this state document within 14 days after your first communication about a claim. It lists rights that include a copy of a detailed estimate within 7 days after the insurer's adjuster generates it.
Condo loss assessment
For a covered type of direct loss, a unit owner policy must include at least $2,000 in loss assessment coverage for assessments arising from that same loss. The deductible is generally no more than $250 per direct property loss, subject to the statute's same-loss rule.
Who is who in a claim
Ask each person who they work for and what role they have before you share information.
Company and independent adjusters
A company employee adjuster works on the insurer's staff. An independent adjuster works for an independent adjusting firm and handles claims on an insurer's behalf. Both act for the insurer, not for the homeowner.
Public adjuster
A public adjuster represents the policyholder under a written agreement and must hold the Florida license required for the work. Florida law treats compensated claim preparation, negotiation, investigation or settlement as public adjusting.
Mediation
F.S. 627.7015 provides a nonadversarial, nonbinding mediation conference for personal lines and commercial residential claims. The insurer generally pays for the conference. A policyholder may rescind a written settlement within 3 business days unless the settlement check has been cashed or deposited. A policyholder who misses a conference may have to pay to reschedule.
We do not handle insurance claims. We do not tell you what your policy covers or what your insurer owes, value or submit a claim, or negotiate with your insurer. For coverage questions, check your policy and your insurer. For a dispute, you may choose to consult a Florida-licensed public adjuster or an attorney.
Talk it through with us
Request a call. We will explain the process. The assessment is done by an independent licensed assessor you hire and pay directly, and if remediation is needed, we sell it under our agreement and a Florida-licensed remediator performs it on our behalf.
Common questions
How do I file a mold claim?
Notify the insurer promptly, protect the property from further damage, keep damaged property and repair receipts, cooperate with the investigation and prepare an inventory with bills. The insurer must acknowledge a claim communication within 7 calendar days. Unless the policy or law provides otherwise, it must begin a reasonably necessary investigation within 7 days after receiving proof-of-loss statements. If the investigation includes a physical inspection, that must occur within 30 days after receipt of those statements, and the assigned adjuster must provide their name and state license number. Insurers issuing personal-lines residential property policies must provide the Homeowner Claims Bill of Rights within 14 days after the initial claim communication. Exceptions and tolling rules apply.
What should I document for a mold claim?
Photograph or video the damage before and after any work. For an NFIP flood claim involving possible mold or moisture damage above the floodwater line, FEMA's June 2025 Claims Manual tells adjusters to consider the time between specified events, including when the building became accessible, the loss was reported, the inspection occurred, damaged materials were removed or cleaned, electrical and HVAC systems were restored, and structural drying began. Keep receipts for emergency measures, an inventory with bills, and any written communication. Keep repair records, but whether missing records affect coverage depends on the policy and claim facts.
How long does the insurer have to pay or deny my claim?
Within 60 days after receiving notice of an initial, reopened or supplemental property claim, the insurer must pay or deny the claim or a portion of it, unless a factor beyond its control applies. It must give a written explanation of the basis for payment, denial or partial denial. Statutory interest applies to late payments of initial or supplemental claims; tolling rules and exceptions also apply. The 60-day rule covers residential coverage and certain commercial property claims involving structures or premises of 10,000 square feet or less.
What is the Homeowner Claims Bill of Rights?
It is a state document the insurer must give you within 14 days after your first communication about a claim. It lists rights including acknowledgment within 7 days; confirmation, upon written request, within 30 days after a complete proof of loss; a copy of the adjuster's detailed estimate within 7 days after the adjuster generates it; and a decision within 60 days, subject to applicable exceptions. It also advises filing claims directly with the insurer, documenting necessary emergency repairs, verifying a contractor's Florida license and requiring proof of insurance.
Should I photograph the damage before cleanup?
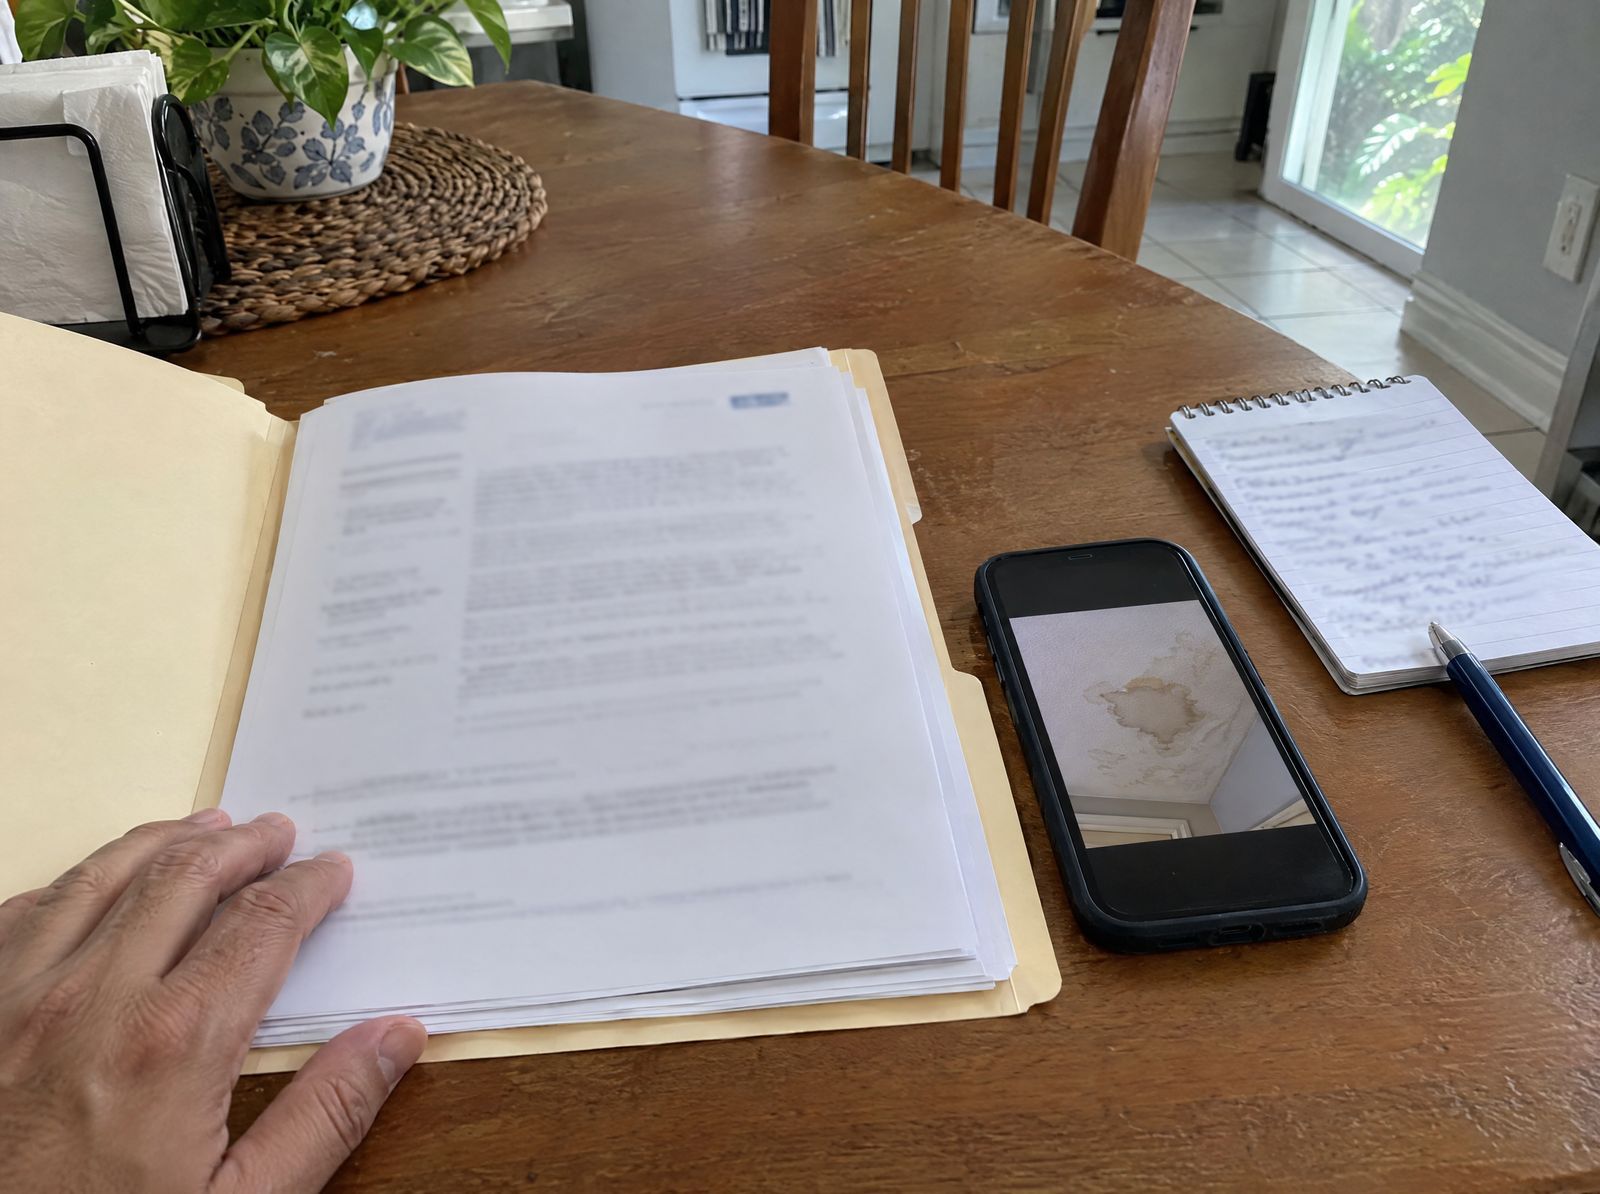
When it is safe, yes. Take dated photos and video before disturbing the area, and again during and after mitigation. Include wide shots and close-ups, the water source if visible, standing water, stained or swollen materials, and moisture readings if a professional shares them. Do not enter unsafe areas or delay emergency mitigation only to take pictures. If you must remove material to stop damage, photograph it first where practical. Keep the original files and back them up. Photos are records, not proof of coverage.
Sources
- Florida StatutesAccessed 2026-09-26
- Florida StatutesAccessed 2026-09-26
- Florida StatutesAccessed 2026-09-26
- Florida StatutesAccessed 2026-09-26
- Florida StatutesAccessed 2026-09-26
- Florida StatutesAccessed 2026-09-26
- Florida StatutesAccessed 2026-09-26
- Florida CFO English residential property mediation guideAccessed 2026-09-26
- Florida StatutesAccessed 2026-09-28
- FEMA / NFIP FEMA NFIP claimsmanual june2025 508cAccessed 2026-09-26